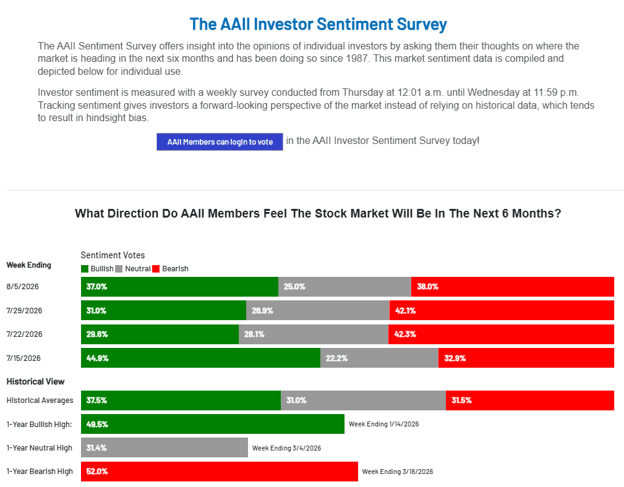
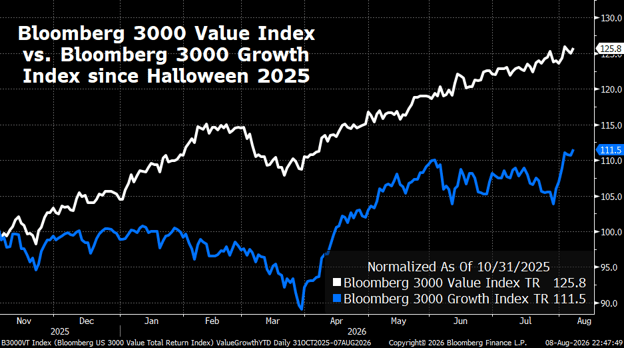
While we can lament that the generals outperformed the soldiers as the capitalization-weighted S&P 500 index jumped 3.6% last week, versus a gain of only 2.4% for the S&P 500 Equal Weight index, and the Bloomberg 3000 Growth index trumped its Value counterpart by more than 260 basis points, cutting into the latter’s large lead since Halloween,…
…August got off to a terrific start for the U.S. equity markets, offering yet another reminder that stocks often climb a wall of worry,...
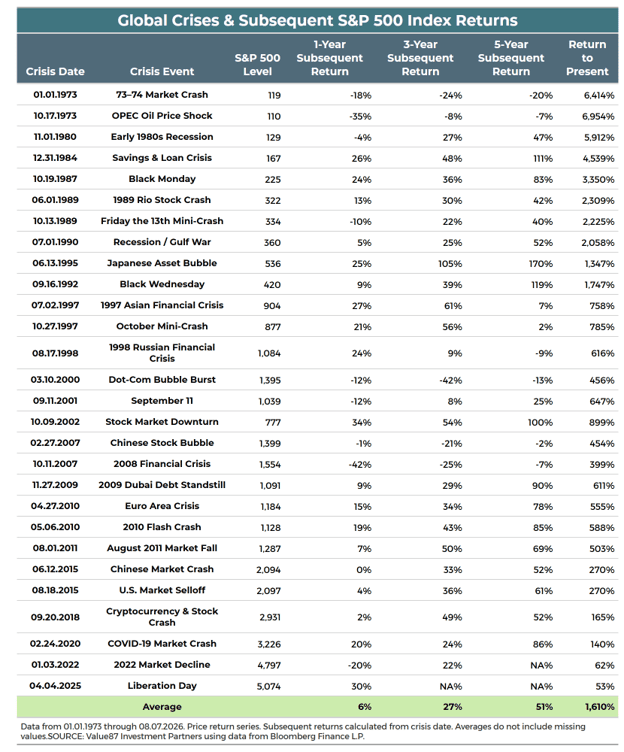
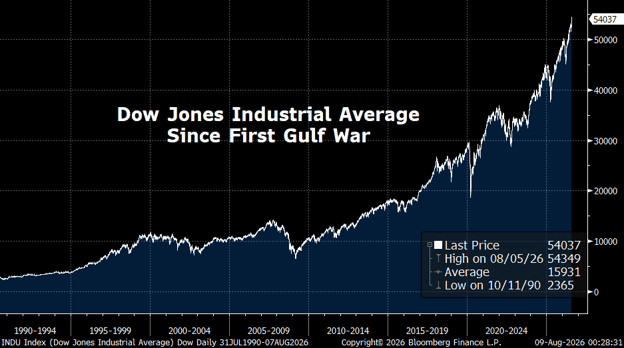
…and that the long-term trend in prices has been higher, as a glance at a chart of the Dow Jones Industrial Average since the start of the first Gulf War in 1990 will attest.
True, some will attribute the rally last week to seeming progress on reopening the Strait of Hormuz, but the umpteenth Memorandum of Understanding with Iran is still very much a work in progress. Of course, there have been hostilities in the Middle East for more than three decades, so U.S. military action in that part of the world has never been a reason for long-term-oriented investors to abandon equities, which is why we always say that time in the market trumps market timing.
Even if one had tomorrow’s headlines in advance, there is no assurance that stocks will move in what might seem like an appropriate direction, as Friday’s disappointing labor report for July could have led to a selloff in stocks. After all, the U.S. economy lost 23,000 jobs last month, compared to an increase of 83,000 that was expected, while May and June’s tallies were revised down by a combined 103,000 jobs.
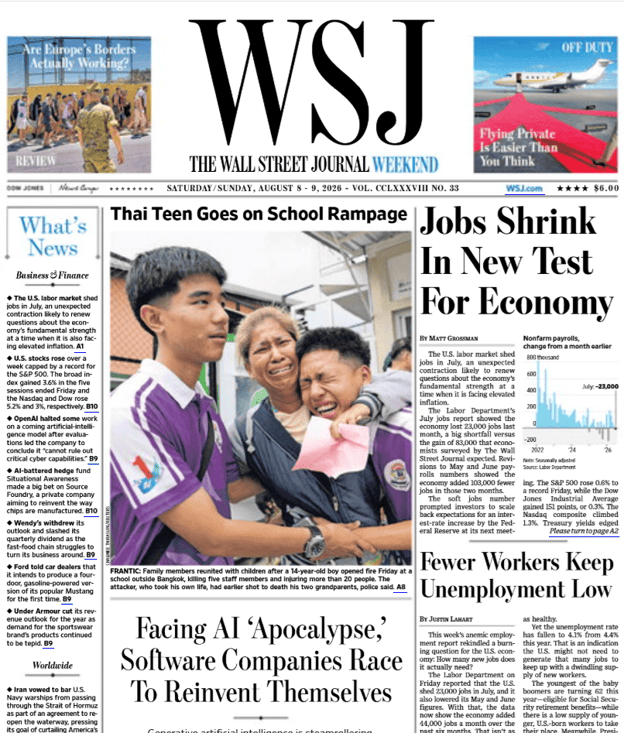
However, the unemployment rate in July dipped to a lower-than-projected 4.1%, while the employment picture looks superb by other measures,…
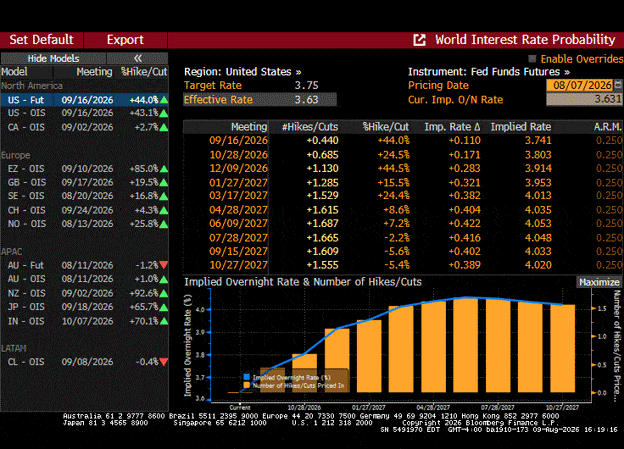
…and the weaker payrolls figure significantly lessened the number of hikes in interest rates from the Federal Reserve predicted by the Fed Funds futures market. Indeed, a week ago, the betting odds suggested the number of hikes by year-end would be 1.48 and by October 2027 would be 1.97, compared to the current figures of 1.13 and 1.55.
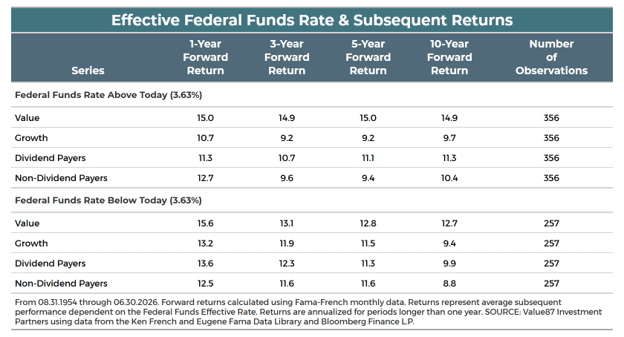
Never mind that data going back to 1954 shows that stocks perform fine, ON AVERAGE, whether the central bank’s lending rate is higher or lower than today’s 3.63% effective rate,…
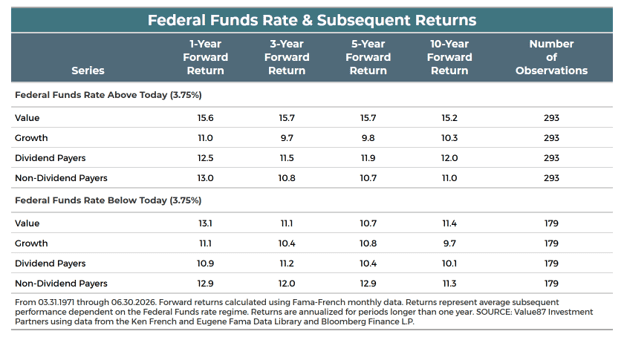
…with the same true of the current 3.75% upper bound of the rate since 1971.
To be sure, the health of the economy is very important as GDP growth over time,…
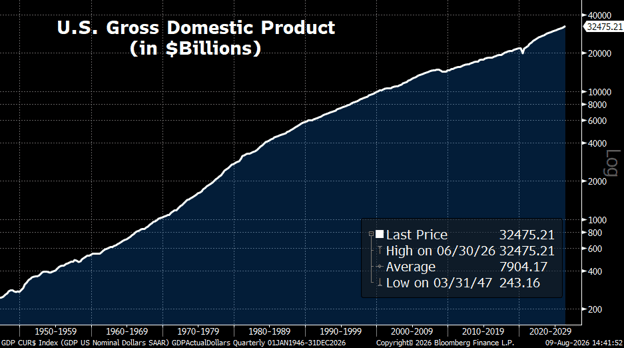
…has driven corporate profit growth, with stocks generally following earnings higher over the long term.
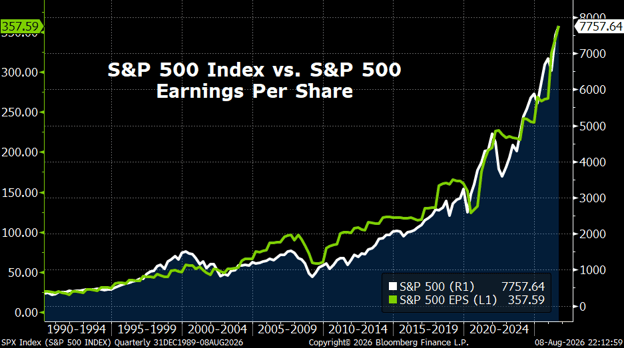
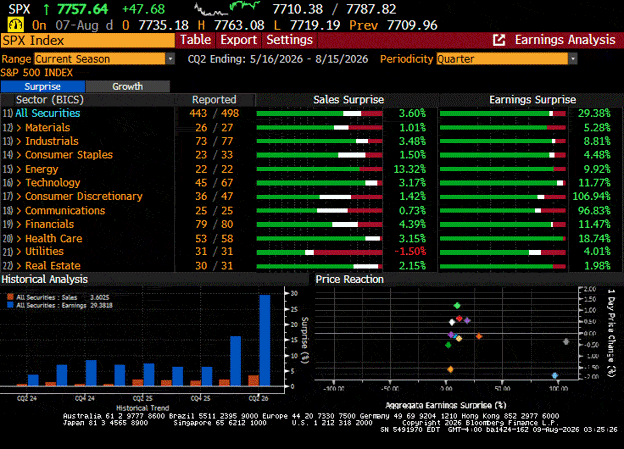
And though real (inflation-adjusted) GDP growth in Q2 was a subdued 1.5%, earnings reports for Corporate America for the latest period have been sensational, with a very-impressive 87.3% of the S&P 500 having exceeded bottom-line forecasts and 68.9% having outkicked top-line estimates, both figures well better than the usual beat rate,…
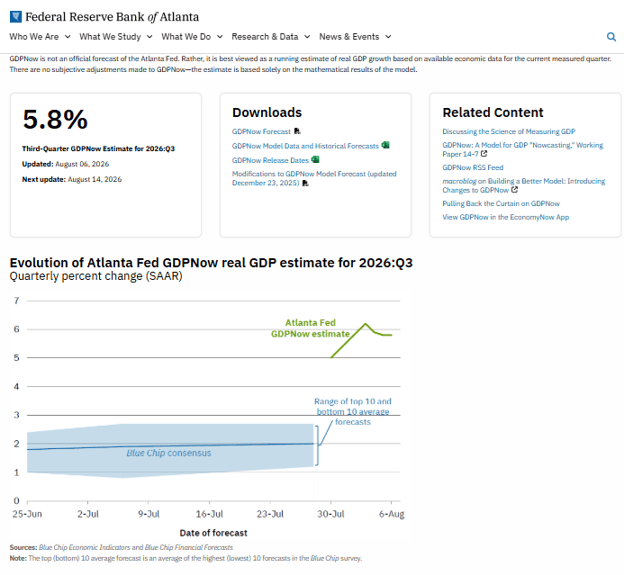
…while the latest projection for Q3 GDP growth from the Atlanta Fed stood at a very robust 5.8%.
Certainly, anything can happen as we go forward, and we realize that we are less than two weeks removed from the Situational Awareness AI-stock meltdown, many of which remain well off their highs (and well above their lows),…
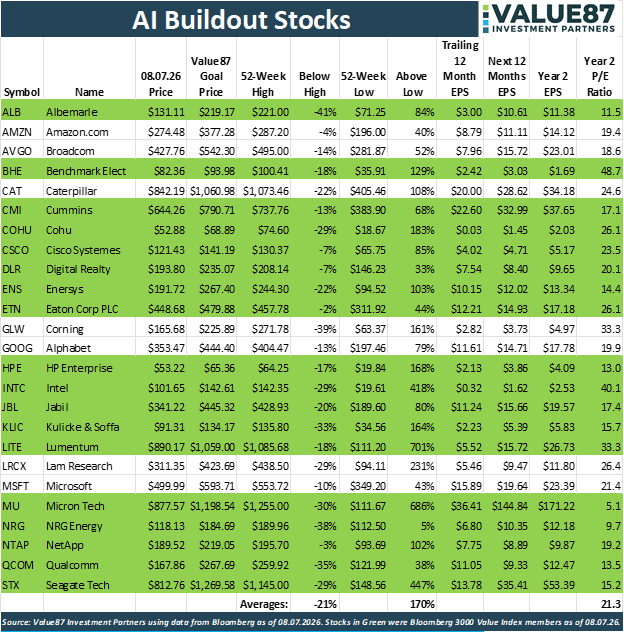
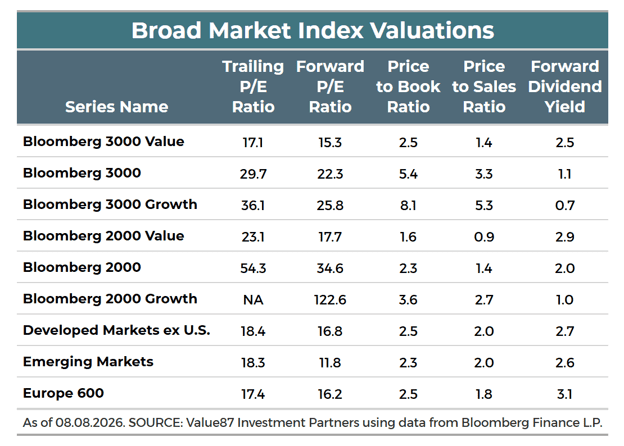
…but we continue to think that valuations for Value stocks remain reasonable.
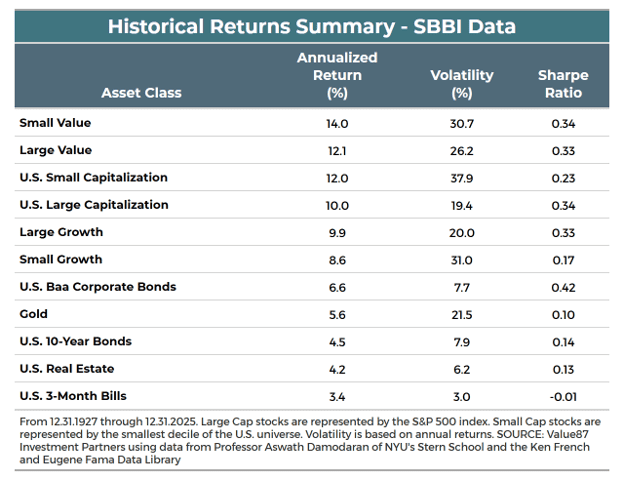
That does not mean that downturns have been banished, as 5% setbacks take place three times a year, ON AVERAGE, 10% corrections happen once a year and even “official” 20% Bear Markets occur every 3.7 years,…
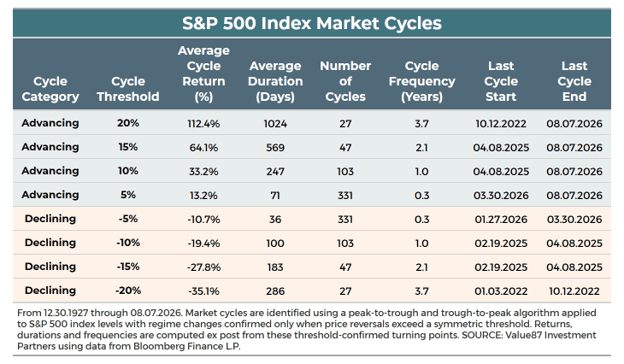
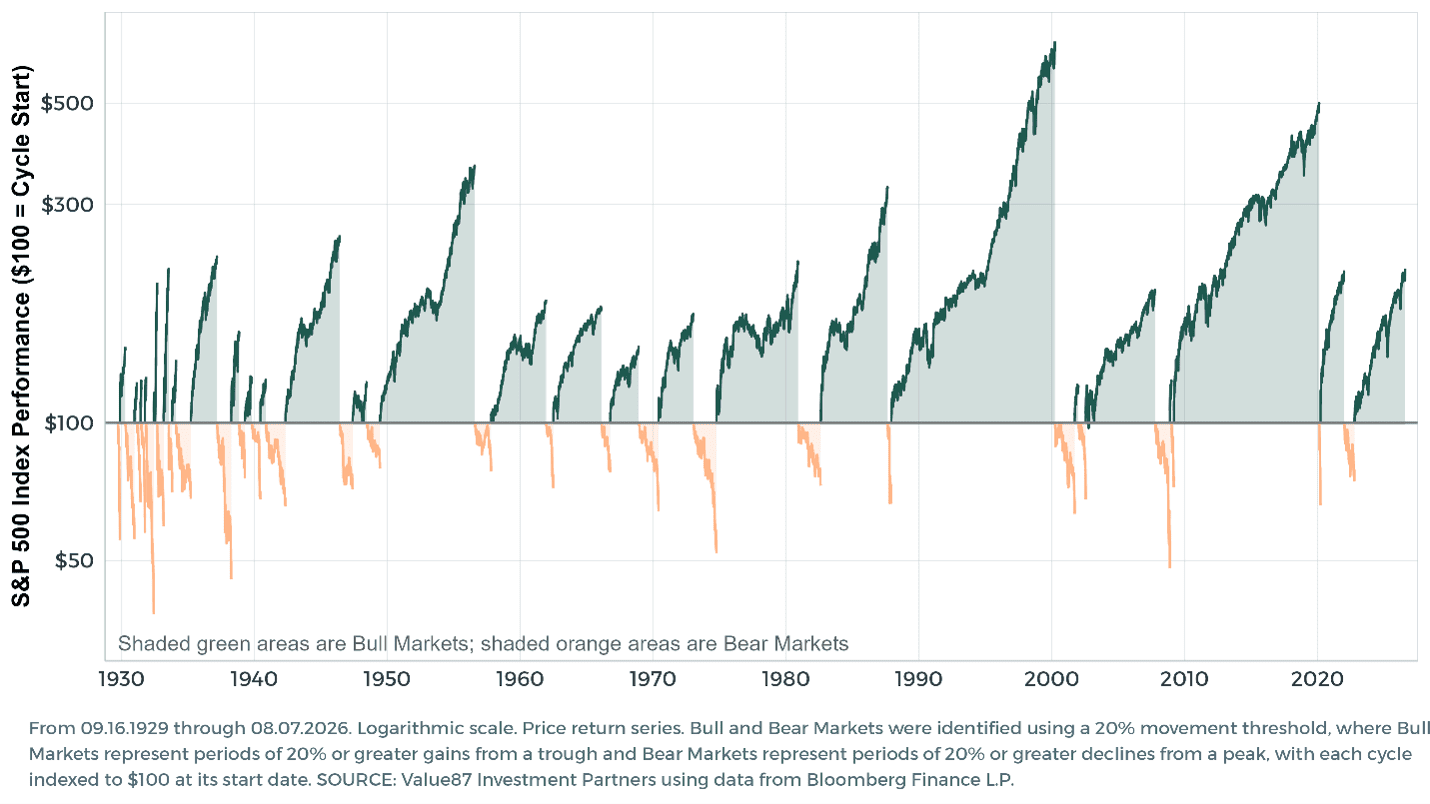
…but the gains when stocks are in Bull Markets dwarf the losses during the times in the red.
We suspect it unlikely that the headlines won’t remain disconcerting, but this is par for the course,…
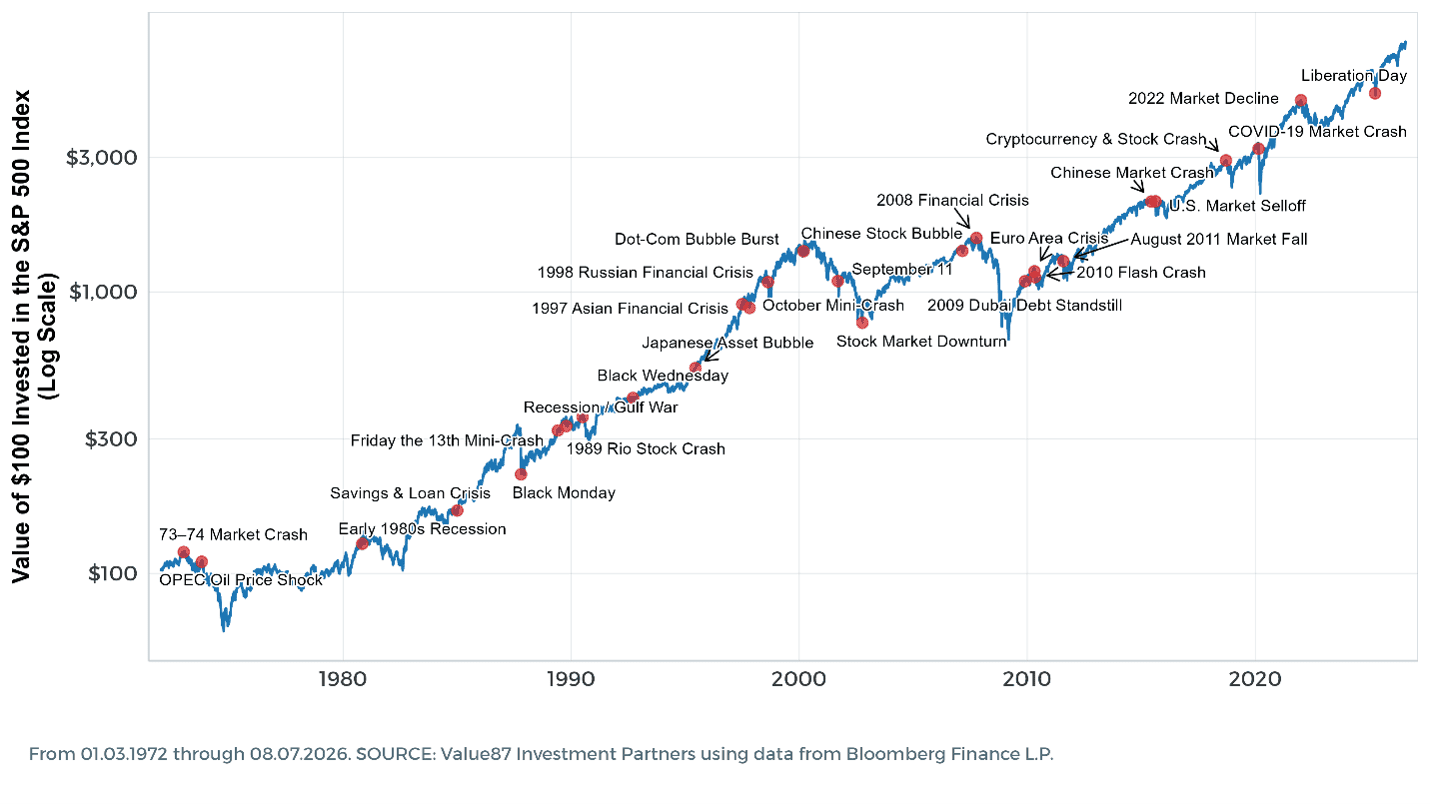
…and we will continue to take the inevitable trips south in stride,…
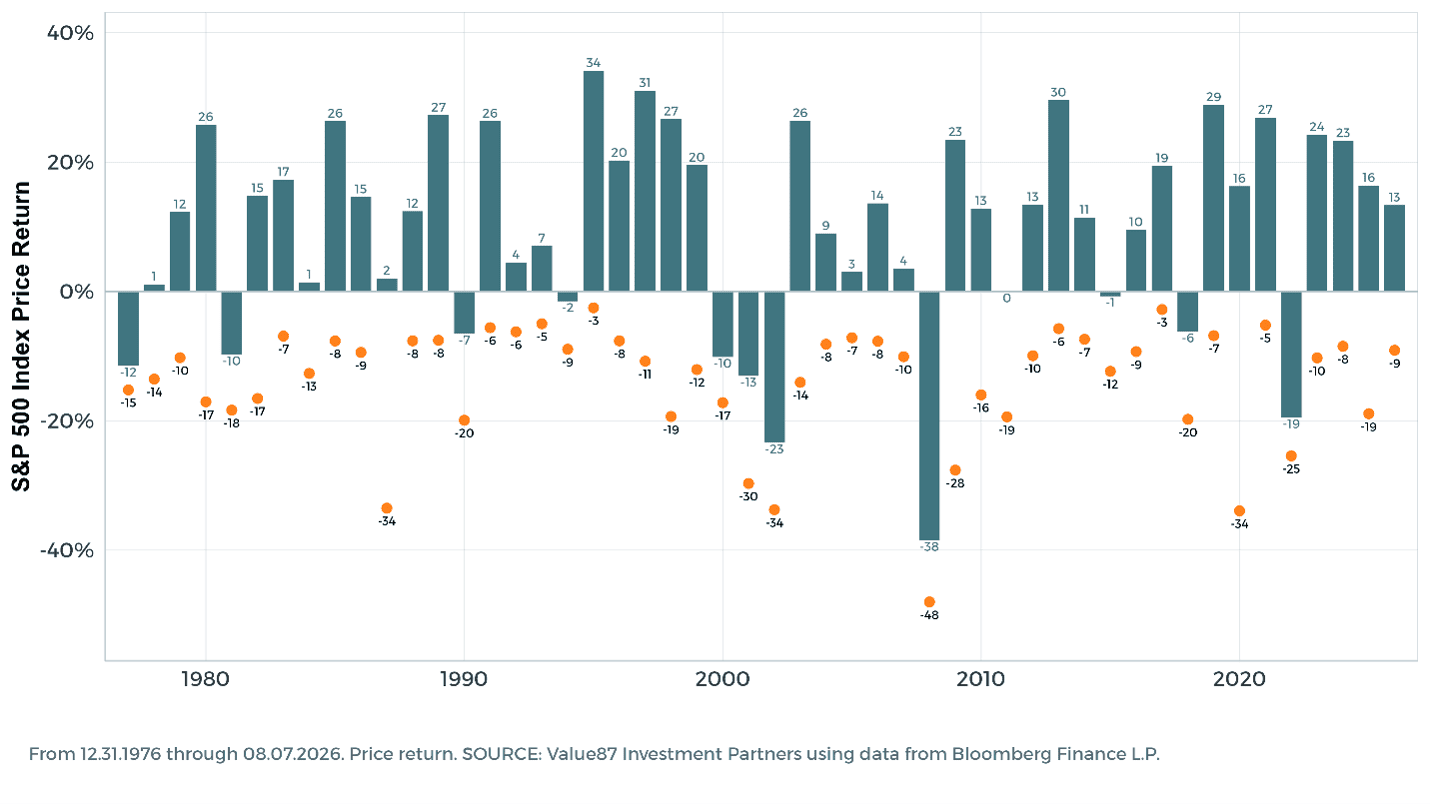
…as we know that investing can be an emotional roller coaster, with more than a few folks missing out on this year’s advance as they forgot that the secret to success in stocks is not to get scared out of them.