It is difficult to complain about a spectacular first half of 2026 in which all the Bloomberg benchmarks in the table below turned in double-digit percentage returns, with the Bloomberg 3000 Value Index topping its Growth counterpart by a sizable margin.
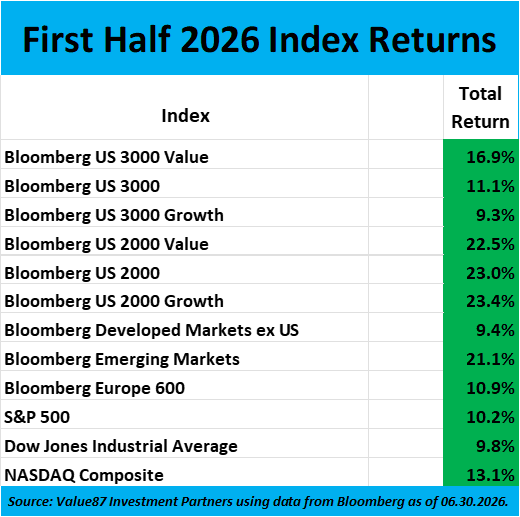
Interestingly, it was a broad-based advance for the Value gauge over the latest two quarters with Health Care, Energy, Industrials and Financials all sizable contributors to total return, along with Technology, led by massive gains in Hardware & Semiconductors.
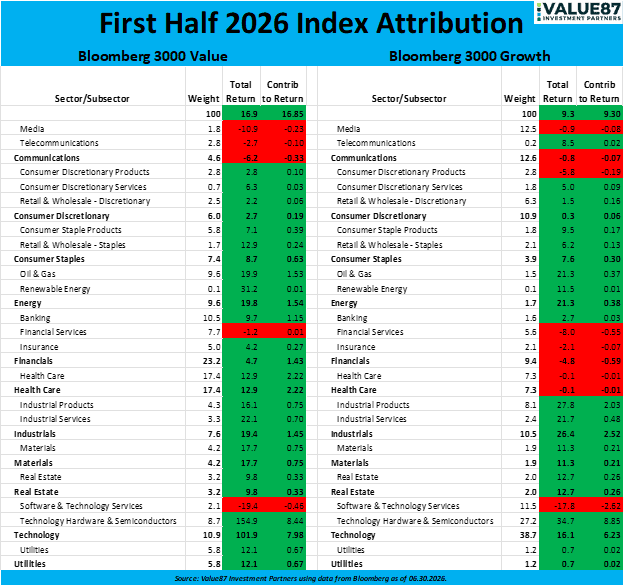
Incredibly, Technology was a larger contributor to total return in the Bloomberg 3000 Value index than it was in the Growth index, with Hardware/Semis representing the top 10 of the best 15 performing stocks held across our various broadly diversified multi-cap-value portfolios. Of course, Software was a miserable performer for us in the first half of the year, with 6 of the bottom 15 returners in that Tech subsector.
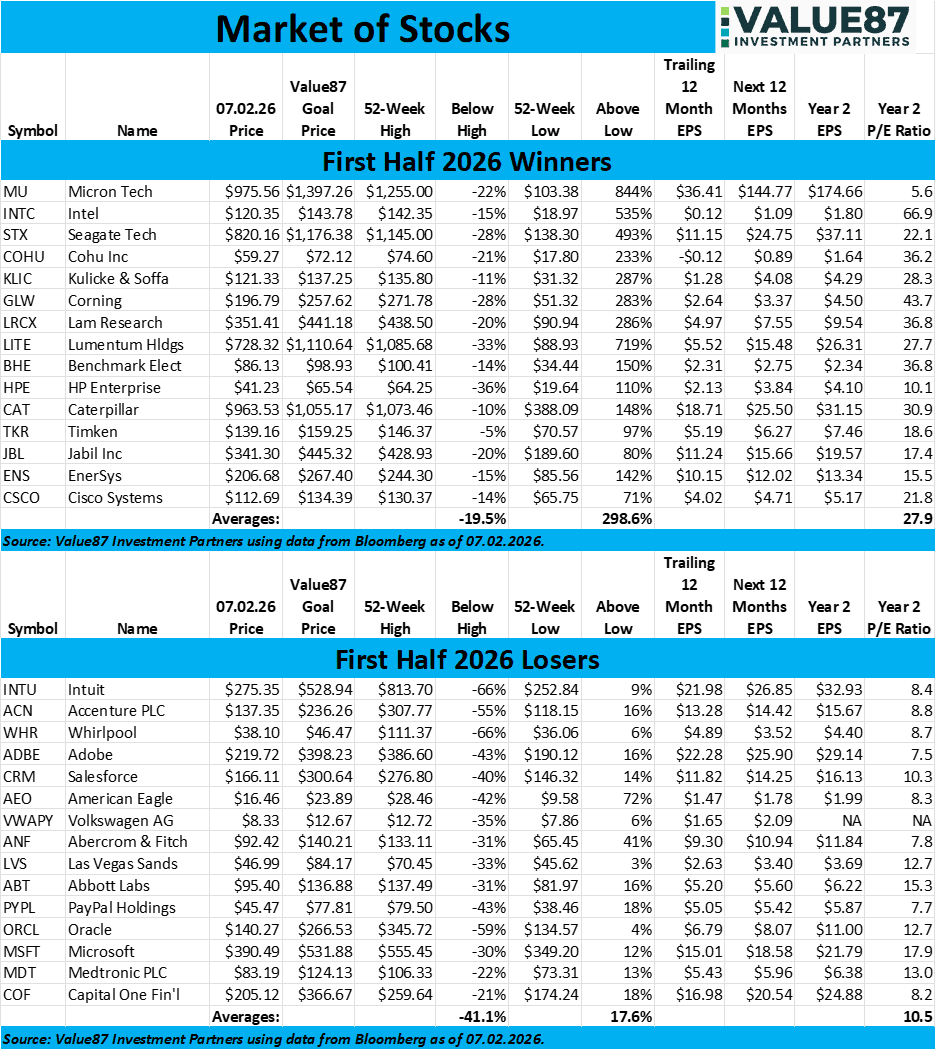
To be sure, Tech is notoriously volatile and traders can bail even faster than they piled in, as evidenced by the tremendous 12.8% average decline posted by those 15 first-half winners…just in the last two trading sessions!
On the flip side, losers can quickly catch a bid, as was the case the past two days with four of the top 5 in-the-red stocks over the first half of 2026.
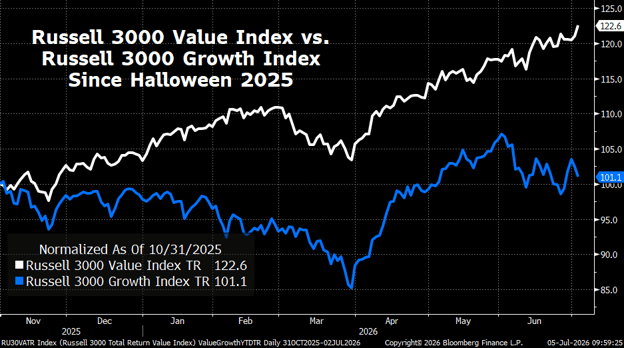
A few days does not a trend make, but action last week proved again that it is always a market of stocks and not simply a stock market. A rising or receding tide seldom lifts or lowers all boats equally, and the lead for the Russell 3000 Value index, which we have long cited in these missives, over the Russell 3000 Growth index now stands at 21.5 percentage points (2,150 basis points) since Halloween.
As a result, our value-oriented investment strategy has long endeavored to take advantage of the dispersion that always seems to occur by harvesting names that have become more expensive and/or grown large in our portfolios, pulling a few weeds that have not performed as expected, and replant the proceeds into other more undervalued companies.
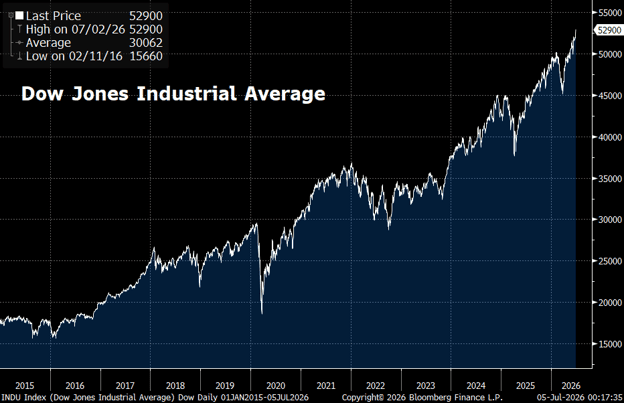
We do this independent of what might be happening with the major market averages, but we note that the long-term trend in stocks, no matter the benchmark gauge evaluated, has been higher, with the Dow Jones Industrial Average closing at an all-time high on Friday.
Certainly, anything can happen as we go forward, so we are always braced for downside movement, with 5% pullbacks happening 3 times per year on average, 10% corrections taking place once a year on average and even 20% Bear Markets occurring every 3.6 years on average.
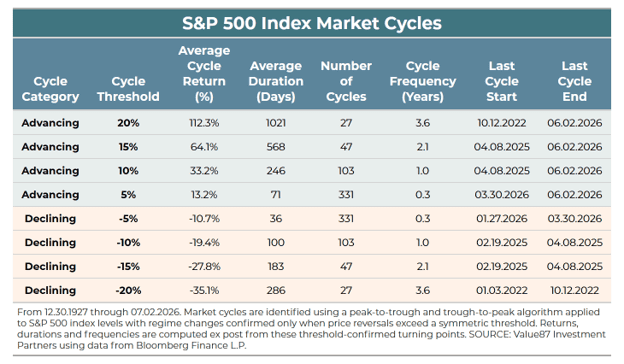
Happily, despite all the disconcerting setbacks along the way, the historical evidence shows that gains of even greater magnitude happen with similar frequency but getting the timing right to avoid the trips south and to participate in the rallies is next to impossible.
As famed money manager Peter Lynch once said, “Far more money has been lost in anticipation of corrections than has been lost in the corrections themselves,” so we have long believed that the only problem with market timing is getting the timing right, especially as the crystal ball remains as cloudy as ever today.
There are plenty of disconcerting headlines these days…as is always the case,…
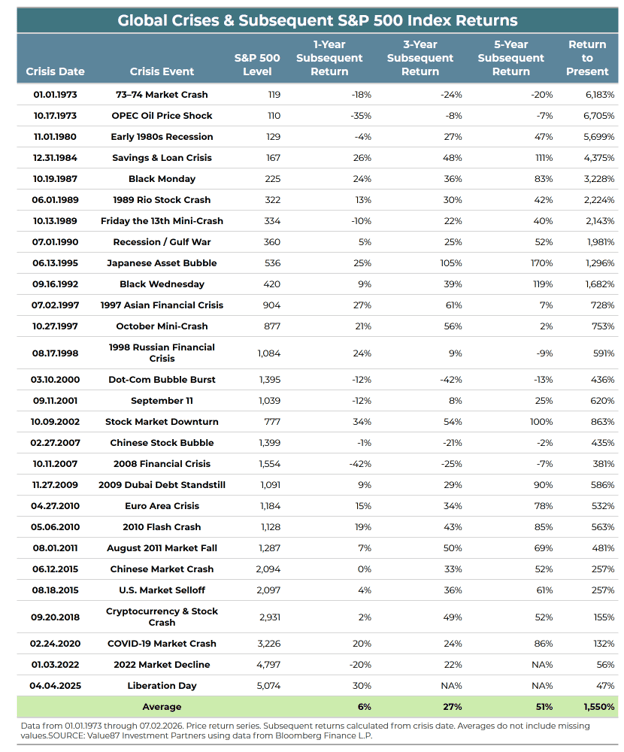
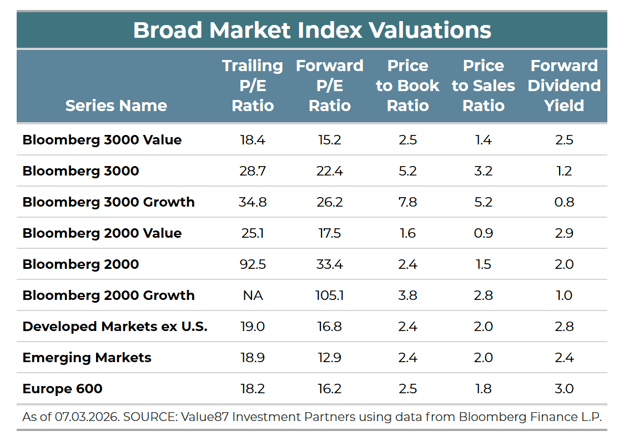
…and we concede that returns in 2023, 2024, 2025 and thus far in 2026 have been well above average, but we see little reason to alter our optimism for the long-term prospects of our stocks. Yes, the health of the U.S. economy remains in question after a disappointing monthly jobs report last week, while market expectations are pricing in at least one hike in the Fed Funds rate by year end, and we are maintaining a little more cash than usual in our portfolios these days. However, we think valuations for the Value indexes remain reasonable,…
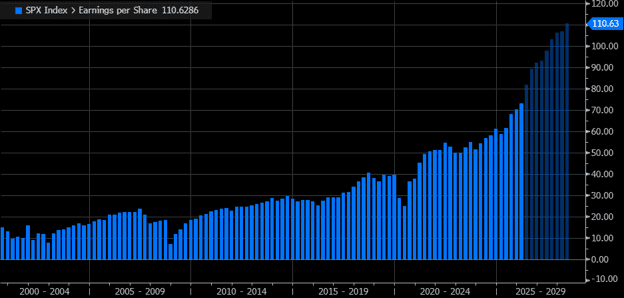
…and we believe that projections of significant profit growth for Corporate America, long the primary driver of higher stock prices, are not unreasonable,…
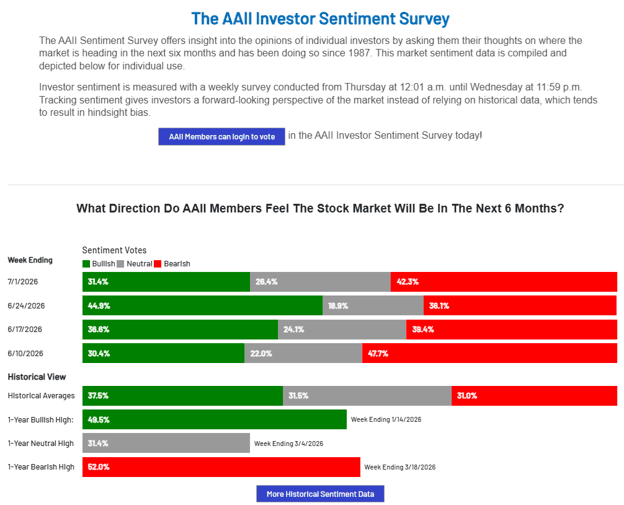
…while we are happy, given our contrarian bent, that folks on Main Street remain skeptical about equities.